
Lawyers can provide needed oversight without sacrificing efficiency
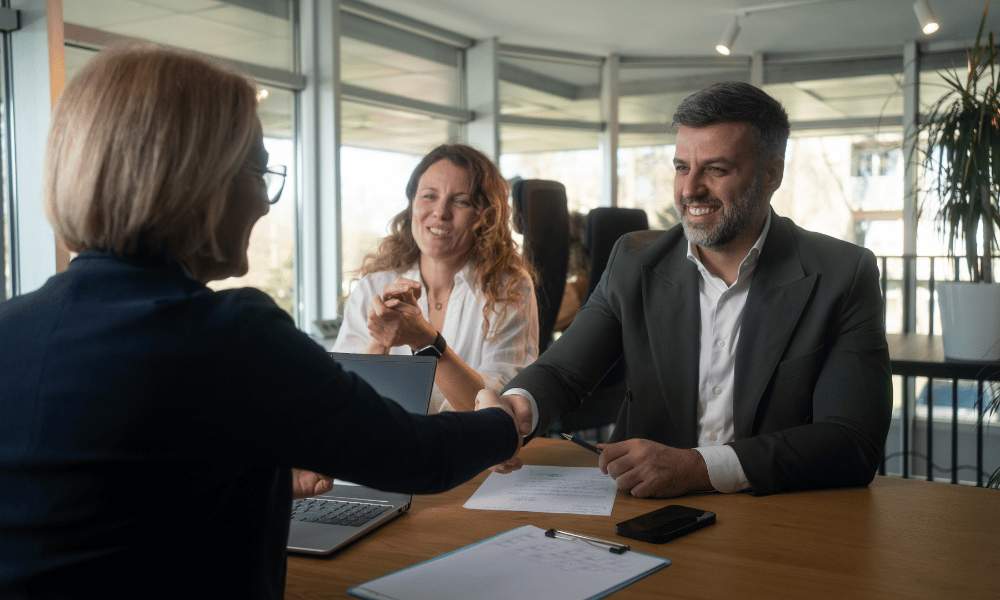

In my legal career, I spent much of my time on residential and commercial conveyancing, including refinance work. It was detailed, relationship-driven work: searching title, coordinating discharges and, most importantly, sitting with borrowers to explain exactly what they were signing.
That last part matters more now than ever before. A borrower refinancing to consolidate debt, manage a separation or restructure other financial obligations is making decisions with real legal and financial consequences. They need more than someone who can move the paperwork through a process. They need someone who can identify an issue, explain what it means and advise them on what happens next.
Over the past two decades, much of that work moved away from law offices and into centralized closing centres. Centralized providers offered lenders and mortgage brokers speed, consistency and lower costs at scale, and in a market where files were relatively standardized and interest rates were stable, the model made a lot of economic sense.
That market has changed.
OSFI's April 2026 Annual Risk Outlook identified real estate secured lending as its top financial system risk. More than 3.1 million mortgages (52 percent of those outstanding) are expected to renew by the end of 2027. CMHC also reported in August that mortgage delinquencies in the Toronto Census Metropolitan Area have risen by 60 percent year over year.
Those numbers reflect a mortgage market under considerably more pressure than the one where centralized refinance models gained ground. Borrowers are navigating higher carrying costs, debt consolidation, changes in lenders, and, in some cases, more complex ownership or title circumstances. That complexity significantly changes what is required at closing.
Centralized models can process straightforward files efficiently, but the challenge arises when the file is no longer straightforward. A CRA lien, a separation affecting ownership, an unexpected title issue or a payout problem can require judgment that does not fit neatly into a standardized workflow. Escalation and reassignment can add time and separate the borrower from the person responsible for resolving the legal issue.
A legal-led model puts legal judgment closer to the transaction. The lawyer or notary reviewing title can identify the problem, advise the borrower on its implications and coordinate the steps needed to resolve it. The advantage is that one person with a professional obligation to the client is accountable for the legal consequences of the transaction.
That has always been the profession's strength. What has changed is the technology surrounding the work. Digital workflows, integrated file management and more efficient title, document and payout processes have narrowed the operational gap that once pushed refinance work toward centralized providers. Legal oversight no longer necessarily means sacrificing speed or convenience.
That matters because a refinance is not simply an administrative transaction. It involves the discharge and registration of mortgages under provincial property law, changes to secured obligations and decisions that can have significant consequences for the borrower. When something unexpected arises, the ability to exercise legal judgment becomes even more important.
There is also a practical reason for real estate lawyers to reconsider refinance work. Canadian resale activity remains subdued, and the Canadian Real Estate Association has revised its 2026 sales forecast downward.
Practices that have traditionally depended heavily on purchase-and-sale transactions are operating in a softer market, and they are feeling it. Refinance work draws on many of the same capabilities firms already have in place and can often be incorporated into a firm’s service offering without needing a major new investment in infrastructure.
But the opportunity for legal professionals is about much more than simply replacing lost transaction volume or one-time refinance revenue – it’s often the beginning of a broader client relationship. The circumstances driving it (for example, a separation, estate planning needs, changes in ownership or broader financial restructuring) may involve other areas where legal advice is valuable for the borrower. It allows lawyers to demonstrate their value at a point when clients may be making some of the most consequential financial decisions they will ever face.
For lenders and brokers, the question should not be whether every refinance needs to be handled differently. Many files will remain straightforward. The more useful question is whether the closing model being used can handle both the straightforward transaction and the complicated one without losing continuity, accountability, or access to legal judgment when needed.
I spent part of my career doing this exact work, and the fundamentals have not changed. A refinance can alter one of the largest financial obligations a borrower will ever assume. When that transaction becomes complicated, legal judgment matters greatly.
What has changed is the market around it. Borrower stress is increasing, refinance files are less predictable, and technology has made legal-led delivery considerably more efficient than it once was.
Refinancing never stopped being legal work. The opportunity for the profession now is to show borrowers, lenders and mortgage brokers that legal oversight and efficient execution are no longer competing choices.